

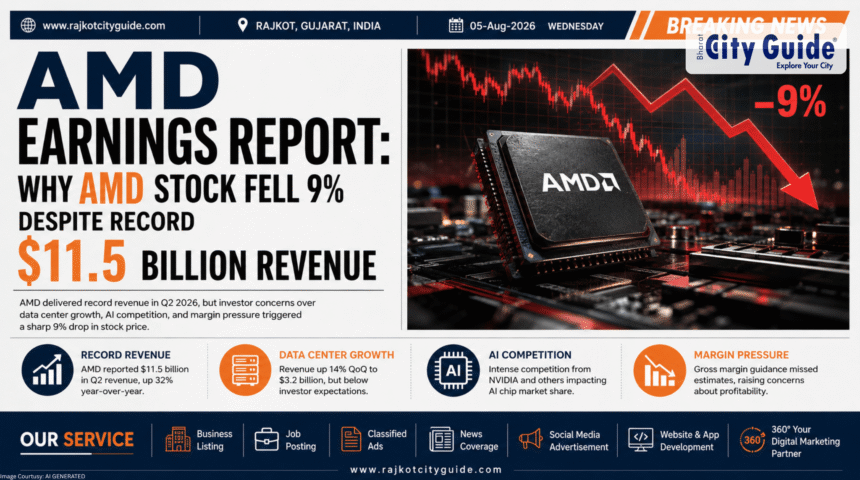
The semiconductor market witnessed a dramatic turn of events following the release of the latest AMD earnings report. Advanced Micro Devices (AMD) reported a record-breaking second-quarter revenue of $11.54 billion, alongside an optimistic $13 billion projection for the third quarter. Despite these impressive figures, AMD stock tumbled nearly 9% in after-hours trading. This sharp drop has left retail investors, tech enthusiasts, and financial analysts in India and around the globe wondering why a record-setting performance resulted in a stock sell-off.
- What is the AMD Earnings Report?
- Current Situation: Understanding the Post-Earnings Stock Drop
- Why Financial Quality and Cash Flow Mattered More Than Revenue
- Key Highlights from the AMD Earnings Report
- Segment Financial Performance Breakdown
- Technical and Financial Metrics Analysis
- The AI Competitive Landscape: AMD Helios vs. Nvidia Ecosystem
- Valuation and Pricing Dynamics
- Advantages of AMD’s Current Market Positioning
- Key Challenges and Drawbacks Facing AMD
- Who Should Consider Investing in AMD Stock?
- Future Expectations and Strategic Roadmaps
- Frequently Asked Questions (FAQs)
- Conclusion
Navigating Wall Street expectations can often feel confusing for investors. A company can beat consensus estimates and still see its share price drop significantly. Understanding the deep financial metrics inside the AMD earnings report is essential for anyone trading tech equities or analyzing the global semiconductor supply chain. This comprehensive breakdown explores the underlying reasons behind the stock decline, the financial performance across key business segments, the competitive AI landscape, and what lies ahead for AMD.
What is the AMD Earnings Report?
An earnings report is a quarterly corporate filing that discloses a publicly traded company’s financial performance. It provides investors with detailed insight into revenue, gross margins, net income, operating expenses, and cash flow. For Advanced Micro Devices, a global leader in high-performance computing, graphics, and visualization technologies, the AMD earnings report serves as a health check on the global tech sector and the broader artificial intelligence boom.
Historically, AMD was known primarily for PC processors and gaming graphics cards, locked in perpetual competition with Intel. Over the past decade, under the leadership of CEO Dr. Lisa Su, AMD has transformed into an enterprise computing powerhouse. Today, the AMD earnings report is watched by institutional and retail investors in India and internationally to gauge the momentum of global cloud infrastructure, data center buildouts, and enterprise AI adoption.
Current Situation: Understanding the Post-Earnings Stock Drop
The latest AMD earnings report for Q2 2026 revealed record financial metrics that, on the surface, appeared exceptionally strong. AMD reported a top-line revenue of $11.54 billion, beating the FactSet consensus estimate of approximately $11.3 billion by roughly 2%. Adjusted earnings per share came in at $1.66, topping expectations of $1.62 per share. Furthermore, the company projected Q3 revenue to reach roughly $13 billion, which surpassed analyst estimates of $12.54 billion.
Despite these positive figures, AMD stock experienced a steep 8.82% sell-off in after-hours trading. To understand why this happened, one must examine market positioning prior to the release. AMD stock had surged 21% over the preceding five trading sessions, including a 7% jump on the day of the release. The market had already priced in an extraordinarily large financial surprise. When the actual figures delivered a modest 2% beat, investors moved quickly to lock in gains. The AMD earnings report revealed that while the company executed well, it failed to exceed the elevated expectations set by the pre-earnings market rally.
Why Financial Quality and Cash Flow Mattered More Than Revenue
For investors assessing the long-term outlook, the recent AMD earnings report contained deeper structural metrics that shifted the market’s attention from top-line revenue expansion to cash conversion and profit margins. Top-line revenue growth measures how fast a company is selling its products, but profit margins and cash flow reveal how efficiently that revenue turns into actual money.
The guidance provided in the AMD earnings report projected Q3 gross margin to remain flat at 56%, identical to Q2. This signaled to the market that even though revenues are scaling aggressively toward $13 billion, the gross profit generated per dollar of sales is not expanding. Investors holding the stock expected higher revenue to unlock operational leverage and yield higher profit margins.
At the same time, the financial statements showed a notable shift in cash generation. Free cash flow dropped 39% quarter-over-quarter, falling from $2.57 billion in Q1 to $1.56 billion in Q2. Operating cash flow fell from $2.96 billion to $2.37 billion, while capital expenditure more than doubled from $389 million to $808 million. The AMD earnings report made it clear that scaling AI data center hardware requires substantial capital investment, temporarily reducing the company’s free cash flow conversion.
Key Highlights from the AMD Earnings Report
- Record Quarter Revenue: Top-line sales reached $11.54 billion, reflecting a 2% beat against Wall Street estimates.
- Strong Q3 Outlook: Revenue guidance projected at $13 billion, representing an impressive 41% year-over-year growth.
- Flat Gross Margins: Gross margin guidance remained flat at 56%, showing limited margin expansion despite rising revenue.
- Data Center Surge: Data center segment revenue doubled year-over-year to $6.72 billion, now accounting for 58% of total company revenue.
- Cash Flow Compression: Free cash flow dropped 39% sequentially to $1.56 billion as capital expenditure doubled to $808 million.
- Competitive AI Pressures: Major enterprise announcements highlighted Nvidia’s strong ecosystem lock-in, placing higher performance pressure on AMD’s AI platforms.
Segment Financial Performance Breakdown
+------------------------+------------------+------------------+------------------+
| Metric / Segment       | Q1 2026          | Q2 2026          | QoQ / YoY Trend  |
+------------------------+------------------+------------------+------------------+
| Total Revenue          | $10.25 Billion   | $11.54 Billion   | Up 12.6% QoQ     |
| Gross Margin           | 55%              | 56%              | Flat / Slight Up |
| Operating Margin       | 25%              | 27%              | Up 200 bps       |
| Free Cash Flow         | $2.57 Billion    | $1.56 Billion    | Down 39.3% QoQ   |
| Capital Expenditure    | $389 Million     | $808 Million     | Up 107.7% QoQ    |
| Data Center Revenue    | $5.10 Billion    | $6.72 Billion    | Up 107% YoY      |
+------------------------+------------------+------------------+------------------+
Data Center Segment
The Data Center division was the primary growth driver featured in the AMD earnings report. Generating $6.72 billion in revenue, the segment grew 107% year-over-year. Driven by strong demand for EPYC server processors and Instinct AI accelerators, data center operations now represent 58% of total revenue. Because AMD relies heavily on this single segment, any future deceleration in cloud provider spending could impact overall corporate growth.
Client Segment (PC Processors)
The Client segment, covering Ryzen desktop and laptop processors, showed steady execution amid a broader PC market recovery. Revenue performance remained solid due to strong adoption of AI-enabled PCs. Ryzen processors continue to capture market share from traditional competitors, providing AMD with a stable cash-generating core outside of server enterprise systems.
Gaming Segment
The Gaming division experienced structural softness as hardware console cycles mature. Sales of semi-custom chips for gaming consoles and standalone Radeon graphics cards posted lower figures compared to prior periods. However, this slowdown was largely anticipated by analysts and was offset by the accelerated growth in the data center division.
Embedded Segment
The Embedded segment, which includes technology acquired from Xilinx, continued its steady recovery cycle. Industrial and automotive customers continue to normalize their inventory levels. While growth here remains moderate compared to data center hardware, the embedded division contributes reliable, high-margin revenue that stabilizes consolidated operations.
Technical and Financial Metrics Analysis
The financial tables within the AMD earnings report show clear trends in operating efficiency alongside higher capital costs. Non-GAAP operating margin improved from 25% to 27% quarter-over-quarter, while operating expenses declined from 31% to 29% of total revenue. This demonstrates effective expense control across core engineering and operational teams.
However, capital intensity grew significantly. Capital spending rose from $389 million in Q1 to $808 million in Q2. As a result, free-cash-flow margin compressed from 25% down to 14%. Supporting next-generation AI hardware platforms requires extensive test infrastructure, advanced packaging procurement, and high-bandwidth memory commitments. The data in the AMD earnings report indicates that AMD must spend aggressively today to capture AI market share tomorrow.
The AI Competitive Landscape: AMD Helios vs. Nvidia Ecosystem
A major factor shaping sentiment around the AMD earnings report is the competitive dynamic between AMD and Nvidia. Elon Musk recently confirmed that SpaceX would build its AI processing infrastructure exclusively using Nvidia platforms, citing Nvidia’s Vera Rubin architecture as a leading AI computing platform. This announcement underscored the significant competitive moat surrounding Nvidia’s hardware and software infrastructure.
Nvidia’s primary advantage lies in its proprietary CUDA software stack, which includes libraries, compilers, and deployment tools optimized over nearly two decades. In contrast, AMD relies on its open-source ROCm software environment to support its Instinct AI systems, including the Helios platform. While ROCm has made significant strides in framework integration and developer adoption, large enterprise clients often prioritize the proven stability and ecosystem maturity of CUDA.
Nevertheless, AMD continues to secure major enterprise AI partnerships. As noted in disclosures surrounding the AMD earnings report, the Helios AI platform is actively being deployed by tech leaders such as Anthropic, Meta, Microsoft, OpenAI, and Oracle. Notably, the Anthropic agreement spans up to 2 gigawatts of MI450 systems. The main challenge for AMD is converting these major commitments into profitable, high-margin revenue streams.
Valuation and Pricing Dynamics
+-----------------------+-----------------------+-----------------------+
| Financial Metric      | AMD Q2 2026 Actual    | FactSet Consensus     |
+-----------------------+-----------------------+-----------------------+
| Total Revenue         | $11.54 Billion        | $11.30 Billion        |
| Earnings Per Share    | $1.66                 | $1.62                 |
| Q3 Revenue Guidance   | ~$13.00 Billion       | ~$12.54 Billion       |
| Gross Margin Guidance | 56%                   | 56.5%                 |
+-----------------------+-----------------------+-----------------------+
Prior to the earnings release, AMD stock traded at an elevated forward price-to-earnings (P/E) multiple, driven by enthusiasm around AI acceleration. When stock valuations reach elevated levels, beating earnings expectations by 2% is often not enough to sustain momentum. The financial data from the AMD earnings report demonstrates that valuation multiples must be supported by continuous gross margin expansion and resilient cash flow generation.
Advantages of AMD’s Current Market Positioning
- Diversified Enterprise Revenue: AMD is no longer just a consumer PC chip maker; over 58% of its sales now come from server data centers.
- Strong Hyperscaler Support: Tier-1 cloud providers including Microsoft, Meta, and Oracle continue to integrate AMD EPYC and Instinct processors.
- Robust Product Roadmap: Next-generation EPYC processors and Helios AI platforms position AMD as a viable alternative in high-performance computing.
- Disciplined Operating Expenses: Operating expenses fell to 29% of revenue in Q2, demonstrating solid internal cost management.
Key Challenges and Drawbacks Facing AMD
- Compressed Cash Conversion: Free cash flow dropped 39% sequentially due to doubling capital expenditures.
- Stagnant Gross Margins: Q3 gross margin guidance remains capped at 56%, limiting short-term profitability gains.
- Dominant Market Competitor: Nvidia’s software ecosystem continues to maintain a strong hold on enterprise AI deployments.
- High Market Expectations: High valuation metrics mean that minor financial misses or flat guidance can trigger sharp stock sell-offs.
Who Should Consider Investing in AMD Stock?
Analyzing the details of the AMD earnings report helps identify which type of investor might consider this stock:
- Long-Term Tech Growth Investors: Investors looking for exposure to global data center expansion and AI infrastructure growth beyond a single supplier.
- Institutional Value-Oriented Tech Buyers: Investors looking to build positions during market pullbacks when valuation multiples pull back to reasonable levels.
- Risk-Tolerant Traders: Market participants comfortable navigating short-term volatility related to quarterly earnings cycles and tech sector sentiment.
Unsuitable for conservative investors seeking steady dividend yields or capital preservation, as semiconductor growth stocks carry inherent market volatility.
Future Expectations and Strategic Roadmaps
Looking beyond the recent AMD earnings report, AMD’s financial trajectory depends on its execution across several strategic priorities over the coming quarters:
- Gross Margin Expansion: AMD must demonstrate that high-volume shipments of Instinct AI processors can push corporate gross margins above 56%.
- Free Cash Flow Recovery: Capital spending must translate into strong cash conversion as manufacturing and packaging scale up.
- Software Ecosystem Adoption: Continued enhancements to the ROCm software stack are vital to lowering switching costs for enterprise software developers.
- Sustained EPYC Dominance: Expanding server CPU market share against traditional legacy competitors remains essential for supporting underlying profitability.
Frequently Asked Questions (FAQs)
Why did AMD stock fall after beating revenue expectations in the AMD earnings report?
AMD stock fell nearly 9% after hours because the company’s 2% revenue beat was not large enough to justify a 21% stock rally in the five sessions leading up to the release. The market had already priced in an extraordinary financial beat, leading to profit-taking.
Was the Q3 revenue guidance in the AMD earnings report considered weak?
No, the Q3 revenue guidance was not weak. AMD projected Q3 revenue of approximately $13 billion, beating the consensus estimate of $12.54 billion and representing 41% year-over-year growth. However, concern centered around the 56% flat gross margin guidance, which limited prospective earnings growth per dollar of sales.
Why did free cash flow decrease in the latest AMD earnings report?
Free cash flow fell 39% sequentially from $2.57 billion to $1.56 billion because capital expenditures more than doubled to $808 million. Operating cash flow also experienced a moderate decline to $2.37 billion, reflecting the higher capital requirements needed to support AI hardware deployment.
How does AMD’s Data Center growth impact the overall business in the AMD earnings report?
Data Center revenue doubled year-over-year to $6.72 billion, now accounting for 58% of AMD’s total sales. While this rapid growth reinforces AMD’s position in enterprise AI and cloud computing, it also makes the company’s overall financial health closely tied to ongoing cloud provider capital spending.
What challenge does SpaceX’s decision pose according to market reaction to the AMD earnings report?
SpaceX’s decision to build AI infrastructure exclusively on Nvidia hardware highlights the competitive moat of Nvidia’s software ecosystem. This dynamic reinforces that AMD must continue improving its software platforms to convince major enterprise buyers to migrate large workloads to AMD hardware.
What operating margin improvements were highlighted in the AMD earnings report?
The AMD earnings report highlighted an improvement in non-GAAP operating margin, which rose from 25% in Q1 to 27% in Q2. Operating expenses as a percentage of overall revenue also declined from 31% to 29%, reflecting disciplined operational cost management across core business units.
Is AMD still winning major corporate customers for its AI platform?
Yes, despite competitive pressures, AMD’s Helios platform is being deployed by key technology platforms, including Anthropic, Meta, Microsoft, OpenAI, and Oracle. A key multi-gigawatt agreement with Anthropic demonstrates strong enterprise demand for AMD’s AI hardware platform.
What key financial metrics should investors track in the next AMD earnings report?
In upcoming reports, investors should monitor whether gross margins can expand beyond 56%, whether free cash flow conversion improves as capital investments mature, and if revenue growth in the Data Center segment remains on a high trajectory.
Conclusion
The latest AMD earnings report highlights a classic market dynamic: strong underlying operational performance crossed with elevated financial market expectations. AMD delivered record revenue of $11.54 billion, achieved 107% growth in its crucial Data Center segment, and provided strong revenue guidance of $13 billion for the third quarter. However, flat gross margin guidance, increased capital expenditure, and a 39% decline in free cash flow led to a post-earnings stock pullback following a sharp pre-earnings rally.
For long-term investors, the pullbacks following the AMD earnings report highlight both the costs and opportunities of the global AI expansion. While capital intensity remains high and software ecosystem competition is fierce, AMD remains a key player in high-performance computing and enterprise data centers. As long as the company executes on its product roadmaps and expands its margins, AMD remains well-positioned at the center of the global technological landscape.