

Introduction
Indian equity markets are closely observing financial sector movements, and the hdfc bank share is positioned squarely at the center of investor attention. As the country’s largest private sector lender, HDFC Bank Ltd has long been considered a structural pillar of the domestic banking sector. The release of the bank’s fiscal first-quarter (Q1) financial results has triggered a wave of reassessments across top global and domestic brokerages.
- Introduction
- What is HDFC Bank’s Core Investment Profile?
- Current Situation and Latest Earnings Update
- Why is the HDFC Bank Share Performance Important?
- Key Highlights from the Q1 Financial Performance
- Detailed Explanation of Key Financial Metrics
- Financial Performance and Operational Specifications
- Brokerage Target Prices and Investment Stances
- Peer Comparison Matrix
- Advantages of Investing in HDFC Bank Share
- Disadvantages and Near-Term Risks
- Who Should Consider the HDFC Bank Share?
- Future Expectations and Strategic Outlook
- Frequently Asked Questions (FAQs)
- Conclusion
While the headline earnings performance showcased steady operational parameters, a deeper look into the financials reveals a complex tug-of-war between strong asset quality and compressed operational margins. Despite minor misses on consensus estimates, leading brokerage houses have maintained a highly optimistic outlook for the long-term compounding path of the stock. For retail and institutional investors tracking the hdfc-bank-share, understanding this post-earnings trajectory is crucial to making informed portfolio allocation decisions.
What is HDFC Bank’s Core Investment Profile?
HDFC Bank Ltd is India’s leading private sector banking institution, commanding an expansive market capitalization that places it among the elite elite entities globally. For over two decades, the lender has built a formidable brand reputation anchored on exceptional credit underwriting, aggressive retail expansion, and high corporate governance standards.
The importance of the hdfc-bank-share to the broader Indian indices—such as the Nifty 50 and the Nifty Bank—cannot be overstated. It acts as an economic bellwether, meaning its individual performance often reflects the credit demand, consumer spending, and systemic liquidity conditions of the wider Indian economy. Following its mega-merger with its parent entity housing finance corporation, the bank has entered a new phase of scale, expanding its balance sheet to tap into under-penetrated structural credit markets across both urban and rural India.
Current Situation and Latest Earnings Update
The immediate market action surrounding the hdfc-bank-share stems directly from its standalone financial performance reported for the April-June quarter.
Core Income and Net Profits
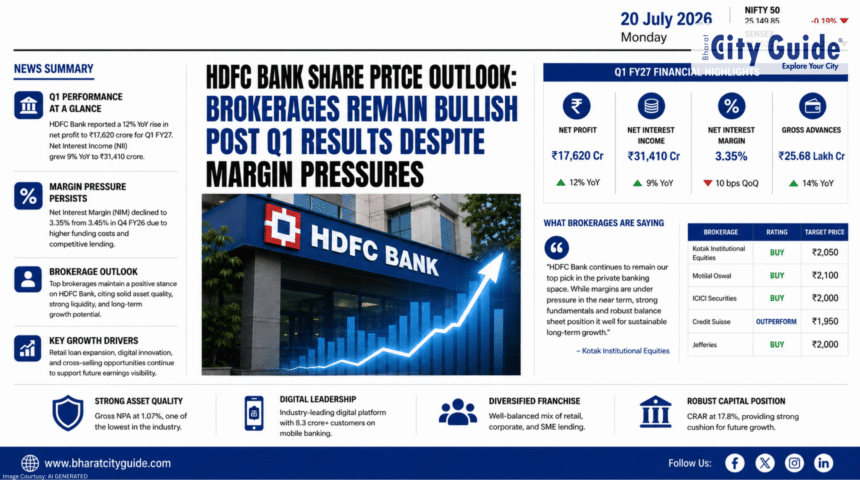
HDFC Bank announced a standalone net profit of Rs 19,059.72 crore for the first quarter, representing a modest year-on-year growth of 4.98 percent. While the single-digit expansion underscores stable income generation, the bottom line fell slightly short of market expectations, missing the CNBC-TV18 consensus poll estimate of Rs 19,332 crore.
Similarly, Net Interest Income (NII)—the difference between interest earned on credit advances and interest paid out on deposits—climbed 6.7 percent to hit Rs 33,535.95 crore. This line item also registered a minor variance against the street estimate of Rs 34,353 crore.
Margin Friction and Deposit Trends
The primary operational challenge evident in this earnings print revolves around Net Interest Margin (NIM) compression. The lender’s NIM stood at 3.26 percent on total assets, marking a multi-quarter low. The squeeze is largely a byproduct of an adverse shift in credit yields and elevated systemic funding costs, with high-cost wholesale deposits keeping the pressure active. Furthermore, the low-cost Current Account Savings Account (CASA) ratio saw a sequential dip to 32 percent from the 34 percent recorded in the previous quarter, emphasizing the aggressive competitive environment for gathering retail deposits.
Asset Quality Parameters
Counterbalancing the margin pressure, HDFC Bank delivered a highly robust performance on the asset quality front, providing a defensive cushion to its overall valuation.
- Gross Non-Performing Assets (GNPA): Logged at 1.17 percent as of June 30.
- Net Non-Performing Assets (NNPA): Maintained at a conservative 0.41 percent.
The marginal sequential uptick in slippages was mostly attributed to routine seasonal factors connected to agricultural loan portfolios, leaving the core structural asset quality pristine.
Why is the HDFC Bank Share Performance Important?
The operational direction of HDFC Bank impacts various components of the financial landscape:
- Systemic Credit Indicators: Steady loan growth metrics show that internal corporate demand and small-to-mid-market enterprises are continually looking for expansion capital.
- FII and DII Allocations: Due to its immense weight in domestic indices, foreign institutional flows into India are highly sensitive to the operational stability of large-cap banking firms.
- Valuation Realignment: A temporary compression in margins creates a visible gap between short-term price adjustments and long-term earnings potential, making it a critical watch point for value-oriented asset managers.
Key Highlights from the Q1 Financial Performance
- Steady Bottom Line: Standalone net profit stood at Rs 19,059.72 crore, showing a stable 4.98% year-on-year increment.
- NII Resiliency: Net Interest Income advanced by 6.7% to Rs 33,535.95 crore, proving steady operational income streams despite rate pressures.
- Pristine Credit Quality: GNPA at 1.17% and NNPA at 0.41% confirm that the bank’s underwriting discipline remains intact post-merger.
- Margin Compression: Net Interest Margin felt the heat of high borrowing costs, settling down at 3.26% on total assets.
- Robust Book Growth: Franchise scale remained evident with healthy underlying momentum across mid-market and corporate credit channels.
Detailed Explanation of Key Financial Metrics
Net Interest Margin (NIM) Optimization
The trajectory of the hdfc-bank-share is tightly linked to how quickly its NIM can normalize. Post-merger operational shifts require the replacement of higher-cost corporate borrowings with lower-cost retail deposits. Management expects a 40 to 50 basis-point reduction in funding costs to unfold over multiple quarters as high-yielding retail credit lines gradually balance out the wholesale funding drag.
CASA Accumulation Strategy
CASA deposits represent the cheapest source of capital for any commercial bank. Given that the bank’s CASA ratio hovered around 32% during the quarter, the primary focus is now shifting toward intensifying deep-tier geographic expansion and leveraging digital channels to build long-tail retail deposit relationships.
Loan Book Composition
While retail credit growth experienced a deliberate, defensive slowdown to protect margins, corporate and small-to-medium enterprise (SME) segments registered healthy operational traction. This rebalancing acts as a tactical buffer, allowing the lender to deploy capital into safe, predictable corporate books while the retail liabilities structure matures.
Financial Performance and Operational Specifications
Understanding the numeric strengths of the hdfc-bank-share requires looking closely at its balance sheet and structural data points:
- Market Capitalization: Stays securely above the Rs 12,000,000 crore milestone, keeping it as India’s premier banking asset.
- Advances Growth: Gross average advances recorded steady structural expansions, driven heavily by commercial and wholesale lending divisions.
- Deposit Growth: Total deposit mobilization maintained healthy double-digit growth year-on-year, illustrating high institutional trust.
- Provisioning Cushion: Provisions saw a minor sequential adjustment, highlighting proactive risk management without straining overall profitability.
- Subsidiary Performance: Strategic arms like HDB Financial Services continue to deliver strong independent profit expansion, providing additive value to the parent entity.
Brokerage Target Prices and Investment Stances
Global and domestic research desks have closely analyzed the Q1 data points to update their models for the hdfc-bank-share.
| Brokerage House | Rating Status | Target Price (INR) | Implied Tactical Upside |
|---|---|---|---|
| Bernstein | Outperform | Rs 1,150 | Over 40% Upside |
| Kotak Securities | Buy | Rs 1,050 | Gradual NIM Recovery Focus |
| Citi Research | Buy | Rs 970 | Factored 13 bps NIM Dip |
Detailed Rationale
- Bernstein’s Perspective: Analysts at Bernstein emphasized that the quarter reflected a highly steady performance supported by healthy balance sheet momentum. Operating efficiency metrics helped defend core profitability, and stable credit traits provided a visible operating cushion. Their target of Rs 1,150 highlights the significant gap between current valuations and structural value.
- Kotak Securities’ Analysis: Their team notes that as systemic liquidity challenges gradually ease out, funding costs will clear a path for incremental margin expansion over the medium term.
- Citi’s Take: While acknowledging the sequential 13 basis-point dip in NIM, Citi retains a constructive view due to tight control over operating costs and disciplined retail credit distribution.
Peer Comparison Matrix
Evaluating the hdfc-bank-share alongside its primary private sector peers highlights its relative valuation position:
- ICICI Bank: Frequently highlighted for strong near-term NIM metrics and core operating momentum, trading at a relatively higher valuation multiple compared to its historic averages.
- Axis Bank: Exhibits solid credit growth but shows higher exposure to retail asset variations, creating a distinct risk-reward profile.
- HDFC Bank: Currently viewed as a highly valuable defensive pick. While its margin compression sits below historical benchmarks, its unmatched scale, solid corporate book, and deep provisioning cushion provide unique long-term downside protection.
Advantages of Investing in HDFC Bank Share
- Unrivaled Market Scale: The sheer size of the post-merger balance sheet allows the bank to participate in massive infrastructure and corporate loan syndications.
- Superior Credit Discipline: Maintaining a Net NPA at 0.41% during volatile macro periods highlights the bank’s operational resilience.
- Compounding Potential: The stock offers an appealing risk-reward balance for patient, long-term investors looking to benefit from the normalization of funding structures.
Disadvantages and Near-Term Risks
- Extended Margin Friction: If systemic liquidity across the Indian banking system remains intensely tight, deposit pricing pressures could prolong the compression of net interest margins.
- CASA Attrition: Failure to push the CASA ratio back above the mid-30s percentage mark could delay the expected reduction in overall funding costs.
- Short-Term Price Consolidation: The slight earnings miss against consensus views could result in a brief period of price consolidation before structural upward movements resume.
Who Should Consider the HDFC Bank Share?
The current investment setup of the hdfc-bank-share makes it highly suitable for specific investor profiles:
- Long-Term Wealth Accumulators: Individuals aiming to capture steady, compounding gains over a 3-to-5-year investment horizon.
- Defensive Portfolio Allocation: Conservative retail market participants seeking stable, blue-chip financial exposure to anchored institutional leaders.
- Value Investors: Market players looking to accumulate high-quality operational franchises during passing integration phases.
Future Expectations and Strategic Outlook
Looking ahead through the remaining quarters of the fiscal year, the path for the hdfc-bank-share relies heavily on execution quality. Management’s primary goal is to prioritize deposit-led growth over aggressive credit distribution, ensuring the loan-to-deposit ratio moves toward long-term targets. As high-cost liabilities mature and are replaced by retail deposits, net interest margins are expected to recover step-by-step. Combined with strong independent contributions from its subsidiaries, the fundamental thesis supporting HDFC Bank’s value creation remains intact.
Frequently Asked Questions (FAQs)
1. What were the key highlights of HDFC Bank’s Q1 results?
HDFC Bank reported a standalone net profit of Rs 19,059.72 crore for the first quarter, achieving a 4.98 percent year-on-year increase. The lender’s Net Interest Income rose 6.7 percent to stand at Rs 33,535.95 crore. Although these figures missed the street consensus poll estimates slightly, asset quality remained exceptionally resilient. Gross NPA came in at 1.17 percent, and Net NPA was maintained at 0.41 percent. The primary area of focus for market participants remains the Net Interest Margin, which compressed to 3.26 percent due to elevated funding costs.
2. Why is the hdfc-bank-share under intense focus after the Q1 announcements?
The hdfc-bank-share is under scrutiny because the bank’s operational performance acts as an economic indicator for the broader Indian banking space. Since it is the country’s largest private sector lender, any variations in its margins, deposit accumulation rates, or asset slippages influence broader institutional sentiment. Investors are currently weighing the bank’s excellent credit quality against its compressed operational margins to determine the stock’s intermediate price direction.
3. What is the target price set by Bernstein for the hdfc-bank-share?
Bernstein has maintained its ‘Outperform’ rating on the hdfc-bank-share, assigning a target price of Rs 1,150 per share. This target price indicates a potential tactical upside of over 40 percent from the stock’s prior closing levels. The brokerage pointed out that the bank’s steady operational quarter, stable balance sheet growth, and pristine credit quality offer an outstanding safety margin for investors, effectively neutralizing the near-term headwinds caused by elevated borrowing costs.
4. Why did HDFC Bank’s Net Interest Margin (NIM) compress during the quarter?
The compression of HDFC Bank’s NIM to 3.26 percent was driven by persistent pressures in funding costs and shifting loan yields. Following its mega-merger, the bank has had to carry a higher mix of wholesale borrowings. Because systemic liquidity in the banking sector remains highly competitive, the bank had to rely on high-cost deposits, which raised its overall cost of funds. Additionally, a sequential drop in the low-cost CASA ratio to 32 percent added to the margin compression.
5. Is the asset quality of HDFC Bank a cause for concern?
Not at all. The asset quality of HDFC Bank remains one of its most compelling advantages. Recording a Gross NPA of 1.17 percent and a Net NPA of 0.41 percent shows exceptional underwriting standards. The minor sequential increase in non-performing assets observed during the quarter was largely tied to seasonal factors within the agricultural loan portfolio. This trend typically reverses in subsequent quarters, indicating that the bank’s core credit book is highly secure.
6. How are other major brokerages rating the hdfc-bank-share post-earnings?
Apart from Bernstein’s bullish target of Rs 1,150, other prominent brokerages have also maintained positive stances. Kotak Securities retained its ‘Buy’ rating with a target price of Rs 1,050, highlighting a gradual margin recovery as funding conditions normalize. Citi Research also maintained its ‘Buy’ rating with a target price of Rs 970, noting that the bank’s highly disciplined cost-to-income controls help offset the near-term compressions in fee income and interest margins.
7. What should retail investors do with the hdfc-bank-share right now?
For retail investors, the hdfc-bank-share represents a classic long-term compounding opportunity. While short-term consolidation may continue due to passing margin headwinds, the bank’s structural growth drivers, unmatched corporate scale, and proactive credit provisions offer solid downside protection. Long-term investors can consider accumulating the stock during market dips, keeping an investment horizon of 3 to 5 years to benefit fully from the post-merger structural integration.
Conclusion
HDFC Bank’s fiscal first-quarter financial performance highlights a transitional phase of operational consolidation. While the minor misses on net profit and net interest income targets reflect the reality of a tight systemic deposit market, the underlying strengths of the franchise remain clear. The bank’s impeccable asset quality, controlled provisioning, and efficient operating costs continue to show its core resilience.
With leading global research desks like Bernstein maintaining an Outperform rating and setting a target price of Rs 1,150, institutional confidence in the hdfc bank share remains strong. Short-term margin adjustments provide a reasonable accumulation window for patient, value-driven long-term investors. As the banking sector’s liquidity dynamics normalize, HDFC Bank is well-positioned to convert its massive operational scale into sustainable value creation for its shareholders.