

Introduction
Retirement planning in India is undergoing its most massive structural shift in decades. For millions of salaried professionals across the country, corporate financial security hinges directly on the decisions made by the Employees Provident Fund Organisation. This central statutory body manages the retirement corpora of India’s formal workforce, ensuring that individuals have access to a financial cushion when they hang up their boots. In a series of sweeping legislative shifts, the framework governing your hard-earned money has been overhauled to align with modern workforce dynamics.
- Introduction
- What is the Employees’ Provident Fund Organisation?
- Current Situation and Latest Updates
- Why is this Important?
- Key Highlights of EPS-2026
- Detailed Explanation of Main Features
- Pension Calculations and Contribution Mechanics
- Governance Framework for Corporate Exempted Trusts
- Advantages of the EPS-2026 System
- Disadvantages and Operational Challenges
- Who is Impacted by These New Rules?
- Implementation Timeline and Future Expectations
- Frequently Asked Questions (FAQs)
- Conclusion
The government has introduced the transition from old frameworks to a highly streamlined, modern structure under the Code on Social Security, 2020. The landmark amendment transforms plans that have been running for 74 years, 50 years, and 31 years respectively under previous acts. These significant changes alter everything from monthly deduction tracking to final retirement payouts. If you are an active contributor, understanding these key changes is non-negotiable for securing your financial future.
This highly detailed guide breaks down the transition from the legacy setup to the newly enacted Employees’ Pension Scheme, 2026 (EPS-2026). We will dive into processing timelines, delay interest rates, employer responsibilities, and how these changes impact your monthly paycheck. Read on to discover exactly how your retirement security is evolving under the new operational directives.
What is the Employees’ Provident Fund Organisation?
The Employees’ Provident Fund Organisation is one of India’s largest social security organizations in terms of both membership and financial volume. Established originally under the Employees’ Provident Fund and Miscellaneous Provisions Act of 1952, its primary objective is to administer mandatory retirement savings schemes for the country’s organized sector workforce. Over the decades, it has served as the bedrock of financial stability for multiple generations of Indian workers.
The organizational infrastructure manages three primary schemes for employees: the core Provident Fund (EPF), the Pension Scheme (EPS), and the Insurance Scheme (EDLI). Together, these programs form an integrated safety net. Contributions made during an individual’s active working years serve a dual purpose: building a lump-sum retirement corpus and providing a lifetime monthly pension post-retirement.
As the Indian economy grows and digitizes, the operational guidelines required a comprehensive modern upgrade. The organization now functions under the broader umbrella of the Code on Social Security, 2020. This alignment ensures greater administrative accountability, enhanced transparency, and faster processing speeds for millions of active corporate subscribers.
Current Situation and Latest Updates
The transition to the new structural regime marks a complete formalization of the Employees’ Pension Scheme, 2026 (EPS-2026). This new scheme completely replaces the legacy Employees’ Pension Scheme, 1995 (EPS-95) and the older Employees’ Family Pension Scheme, 1971. While existing pensioners will continue to receive their disbursements without any disruption, all new registrations and future calculations are integrated directly under this modern directive.
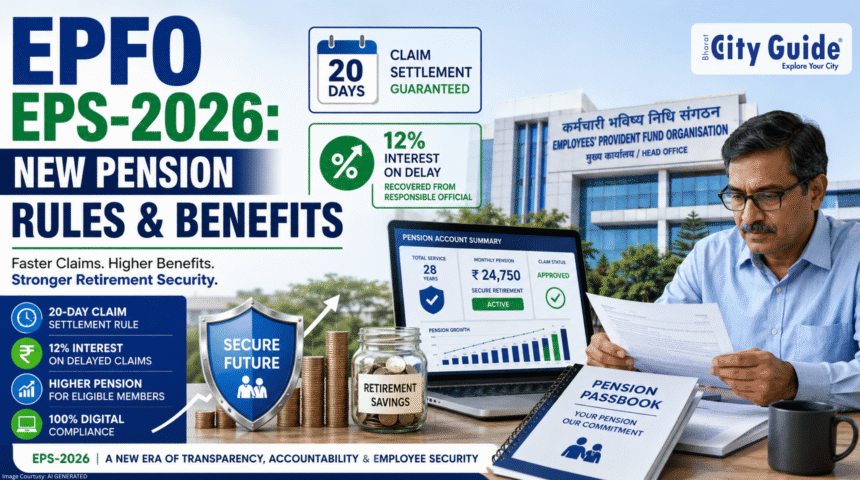
A primary operational highlight of the current update is the strict implementation of a 20-day claim settlement deadline. The Employees’ Provident Fund Organisation is now legally mandated to either fully process and settle a complete pension claim within 20 days or flag specific documentation errors to the applicant within that same period. This eliminates the long administrative delays that historically left senior citizens waiting months for their retirement payouts.
To back this timeline with teeth, the regulatory authority has introduced a mandatory 12% interest penalty on delayed claims. If an eligible claim is stalled by administrative bottlenecks without a legally justifiable reason, the organization must pay 12% annual interest on the delayed corpus. Crucially, the regulations state that this interest will be directly recovered from the salary of the responsible regional official, introducing a wave of personal accountability.
Why is this Important?
These changes carry massive significance for the everyday salaried professional in India. For decades, navigating retirement benefits involved intense paperwork, manual verification, and prolonged administrative uncertainty. The implementation of EPS-2026 by the Employees’ Provident Fund Organisation brings legal predictability into the retirement planning equation, making the system highly transparent for young and old earners alike.
From an industry perspective, the focus on absolute digital compliance changes how corporate human resource and finance teams operate. It reduces manual intervention, cuts down on compliance fraud, and ensures that employee records are updated systematically in real time. For companies managing exempted private trusts, the framework brings strict oversight to prevent fund mismanagement.
The macro-economic impact is equally noteworthy. By anchoring the pension and fund rules under the unified Code on Social Security, the Indian government is strengthening the national social security network. It ensures long-term sustainability for the pension pool while protecting low-income workers through strict minimum return guidelines.
Key Highlights of EPS-2026
The structural transition introduces several foundational shifts. Here is a summary of the major high-level changes:
- Rebranding and restructuring of the framework into the Employees’ Pension Scheme, 2026.
- Mandatory 20-day claim processing window for all valid retirement applications.
- Compulsory 12% annual interest payout on delayed settlements, recovered directly from delinquent officers.
- formal addition and streamlined integration of higher pension calculation rules for eligible members.
- Guaranteed minimum interest return of not less than 8.5% on future government contributions invested in the Public Account.
- Total transition to electronic workflows, requiring mandatory digital compliance from all covered employers.
- Modern governance frameworks, including dematerialized investment reporting for independent corporate trusts.
- Flexible emergency provisions allowing the central government to temporarily adjust contribution rates for up to three months during crises.
Detailed Explanation of Main Features
1. The 20-Day Claim Settlement Rule
The new operational standard requires the Employees’ Provident Fund Organisation to process complete pension applications within 20 days. If the application contains missing data, formatting errors, or incorrect bank details, the system must notify the applicant within the same 20-day window. This completely eliminates the open-ended processing timelines of the past. For retiring employees, this ensures that their monthly pension stream begins almost immediately after their final corporate working day.
2. 12% Interest Penalty on Delays
To enforce administrative efficiency, any delay past the 20-day limit without a valid legal cause triggers an automatic 12% annual interest penalty on the accrued pension dues. This amount is calculated from the day the application passed its deadline up to the actual disbursement date. By recovering this penalty directly from the responsible official’s salary, the system enforces individual accountability at the bureaucratic level, prioritizing consumer protection.
3. Structural Formalization of Higher Pension Provisions
Following historical legal disputes and the landmark Supreme Court judgments regarding higher pension contributions, EPS-2026 officially integrates these provisions into the core text of the scheme. For employees who legally opted for contributions based on their actual higher salary rather than the statutory wage ceiling, the employer’s contribution towards the pension fund adjusts to 9.49% to accommodate the additional pool. This provides clear, codified security for higher-bracket earners without administrative confusion.
4. Minimum Returns on Government Contributions
The funding of the pension pool relies heavily on regular employee, employer, and state contributions. Under the new guidelines, future central government contributions made into the pension fund will be securely maintained in the Central Government Public Account. The state assures a guaranteed minimum return of 8.5% on these specific balances. This provides a rock-solid financial foundation for the fund, ensuring it can weather inflationary periods and maintain long-term payouts.
5. Mandatory Employer Digital Compliance
Under the updated guidelines, employers can no longer rely on hybrid or paper-based documentation systems. From online filing of returns and digital member accounting to electronic claim submissions and e-inspections, every single metric must reflect inside the centralized portal. If an employer fails to maintain real-time digital records, the automated system flags the account, locking out non-compliant firms from standard clear certificates and triggering fast compliance audits.
Pension Calculations and Contribution Mechanics
The math behind your monthly retirement accumulation remains highly structured. While the overarching administrative policies have shifted under the Employees’ Provident Fund Organisation, the foundational mathematical formula used to calculate your monthly pension distribution remains consistent to ensure continuity.
The standard calculation formula is as follows:
$$\text{Monthly Pension} = \frac{\text{Pensionable Salary} \times \text{Pensionable Service}}{70}$$
The “Pensionable Salary” is determined by taking the average of an individual’s basic salary along with any applicable dearness allowance over the final 60 months of employment preceding their exit from the fund. The “Pensionable Service” tracks the total number of active contribution years.
The contribution division operates seamlessly across standard accounts:
- Employer Contribution to EPF: 3.67% of the basic wage.
- Employer Contribution to EPS: 8.33% of the basic wage (capped at the statutory ceiling unless a higher pension option is formally active).
- Employee Contribution to EPF: 12% of the basic wage.
- Government Contribution to EPS: 1.16% of the wage ceiling.
Governance Framework for Corporate Exempted Trusts
Many large corporate organizations in India operate independent, exempted provident fund trusts. Instead of depositing monthly employee deductions directly into the central pool managed by the Employees’ Provident Fund Organisation, these private trusts handle the capital in-house while mirroring or exceeding public interest rates.
The EPS-2026 guidelines introduce a highly rigorous monitoring layer for these private corporate entities. Trust boards must strictly implement electronic accounting systems and conduct mandatory annual independent audits. Furthermore, all physical paper investments must transition completely into dematerialized accounts.
Delayed filing or mismatching balances will trigger severe institutional penalties. If an independent corporate trust fails to meet the strict reporting deadlines, the organization risks losing its exempted status entirely, forcing a mandatory transfer of all accumulated employee wealth back into the primary public pool.
Advantages of the EPS-2026 System
The structural evolution brings clear, measurable benefits to millions of workers across the country:
- Elimination of Administrative Delays: Retiring professionals no longer have to follow up manually with local offices for months to receive their legitimate pension orders.
- Enhanced Financial Protection: The introduction of the 12% interest penalty protects citizens from bureaucratic apathy and systemic delays.
- Code-Level Legality: By embedding higher pension rules directly within the text of EPS-2026, future calculation conflicts are eliminated.
- Corporate Accountability: Strict digital filing protocols prevent unscrupulous employers from deducting money from salaries without actually depositing it with the authorities.
- Guaranteed Fund Solvency: The 8.5% minimum return guarantee on government contributions keeps the retirement pool financially viable against inflation.
Disadvantages and Operational Challenges
While the updates offer major improvements, certain areas require careful attention:
- Technological Barriers for Small Firms: Micro-enterprises operating in remote areas may face initial operational friction adapting to total digital compliance.
- Static Minimum Pension Cap: Despite intense demands from trade unions across India to increase the base pension from Rs 1,000 to Rs 7,500, the baseline minimum remains unchanged in the current rollout.
- Deficit Management: The long-term actuarial valuation of the pension pool shows structural deficits, meaning the system must run at peak efficiency to maintain these high return guarantees over the next few decades.
Who is Impacted by These New Rules?
The modernized guidelines rolled out by the Employees’ Provident Fund Organisation directly affect every stakeholder inside India’s formal employment landscape.
For young professionals entering their very first corporate jobs, the new system means their entire retirement lifecycle will track smoothly across a unified digital record. They benefit from automated portal transfers when switching jobs and clear visibility over their long-term pension trajectory.
For veteran corporate employees approaching retirement age, the changes offer immediate peace of mind. The strict 20-day resolution timeline and penalty parameters guarantee that their retirement transitions will be handled professionally and transparently.
Implementation Timeline and Future Expectations
The updated guidelines under EPS-2026 are already live and operational across the country. All active claim applications, compliance tracking, and automated job-switch transfers are running via the modernized central portal architecture.
Looking ahead, industry experts anticipate that policy updates might address the statutory wage ceiling itself. There are active discussions regarding shifting the historical monthly basic salary cap from Rs 15,000 up to Rs 25,000. If implemented in the coming years, this move would automatically increase monthly pension pools, leading to substantially higher final payouts for the next generation of retirees.
Frequently Asked Questions (FAQs)
1. What is the role of the Employees’ Provident Fund Organisation in managing EPS-2026?
The Employees’ Provident Fund Organisation is the primary statutory administrator responsible for enforcing the modern rules of the Employees’ Pension Scheme, 2026. The organization oversees monthly corporate data filings, manages the collection of pension contributions from employers, invests funds according to safety guidelines, and processes final monthly pension disbursements for eligible retired citizens across India.
2. How does the 20-day claim settlement rule benefit retiring employees?
Under the legacy framework, processing a retirement claim could take months due to physical paperwork verifications. The modern rule legally mandates that the retirement authority must process a complete application within 20 days. If there are any document errors, the applicant must be informed within this exact period, allowing fast corrections and minimizing financial breaks for senior citizens.
3. What happens if the retirement body delays my pension claim settlement?
If a valid, error-free pension claim is delayed beyond the statutory 20-day limit without a legitimate legal justification, an automatic annual interest penalty of 12% is applied to the delayed payment. To ensure strict compliance and prevent internal administrative laziness, the rules dictate that this interest expense will be recovered directly from the salary of the errant regional official.
4. Has the basic formula for calculating my monthly pension changed under EPS-2026?
No, the mathematical core used to calculate your monthly pension distribution remains exactly the same to ensure continuity. The standard calculation multiplies your pensionable service years by your average pensionable salary over the final 60 months of service, dividing the entire product by 70. This ensures that your accumulated pension weight tracks predictably with your employment duration.
5. What are the digital compliance rules for companies under the new pension guidelines?
Employers must handle all records through online systems. This includes electronic filing of monthly returns, automated digital member account creation, and online claim submissions. Companies can no longer use offline methods. Failure to do so flags the account instantly, blocking clear certificates and initiating regulatory audits.
6. Will existing pensioners see any changes or disruptions to their monthly income?
No, existing pensioners who are currently receiving their monthly retirement payouts under the older EPS-95 or 1971 frameworks will face absolutely no disruption. Their existing pension rights are fully protected, and disbursements will continue on time. The administrative upgrades are designed to enhance speed and data accuracy for future processing workflows without impacting active beneficiaries.
7. Can I still apply for an early pension under the updated rules?
Yes, members who have completed at least 10 years of eligible service can choose to opt for an early retirement pension starting from the age of 50. However, choosing an early payout attracts a standard reduction penalty of 4% for every year you draw the pension before reaching the standard superannuation retirement age of 58 years.
Conclusion
The transition to the Employees’ Pension Scheme, 2026 marks a watershed moment for social security management in India. By replacing decades-old frameworks with a streamlined structure under the Code on Social Security, the Employees’ Provident Fund Organisation has significantly elevated its operational standards. The changes successfully strike a balance between strict corporate digital accountability and essential consumer protection safeguards.
Features such as the enforceable 20-day claim settlement deadline and the 12% interest penalty on administrative delays show a genuine shift toward employee-centric governance. While structural challenges like increasing the base minimum pension cap remain open for future debate, the operational foundation built here sets a highly progressive benchmark for national retirement tracking.
For every active corporate worker, keeping tabs on your monthly account statements and ensuring your digital profile details match your documentation perfectly is the best way to leverage these updates. As India’s formal employment sector continues to expand, these modernized guidelines ensure that your decades of hard corporate work translate into a reliable, secure, and hassle-free post-retirement life.
For an explanatory breakdown of the step-by-step practical process regarding how claims are logged into the digital portal under the new guidelines, you can watch this EPFO Pension Claim Guide. This video details how the updated system processes documentation to ensure you receive your settlements within the mandated time frame.