

Introduction
Every year as July approaches, a massive chunk of Indian taxpayers fall into a familiar pattern of procrastination. A significant reason for this delay is the psychological safety net of a potential itr deadline extension. Taxpayers often assume that the government will push the traditional July 31 cutoff date further into August or September, giving them extra time to gather documents and file their returns.
- Introduction
- What is the ITR Deadline Extension Trend?
- Current Situation and Latest Updates for AY 2025-26
- Why Early Filing and Avoiding the Extension Trap is Crucial
- Key Highlights: The True Cost of Delaying Your ITR
- Detailed Complications of Relying on an ITR Deadline Extension
- Statutory Penalties and Financial Implications of Missing the Deadline
- Step-by-Step Checklist for a Penalty-Free ITR Filing
- Advantages of Timely Filing vs. Waiting for an Extension
- Who Benefits the Most from Early Filing?
- Future Expectations: The Paradigm Shift in Indian Tax Administration
- Frequently Asked Questions (FAQs)
- Conclusion
However, banking on an itr deadline extension is a high-risk financial strategy that can easily backfire. The Income Tax Department has progressively tightened its compliance infrastructure, making last-minute extensions the exception rather than the rule. Operating under the assumption that the deadline will change often leads to severe financial penalties, mounting interest on outstanding taxes, delayed refunds, and immense last-minute stress.
If you are currently waiting to see if the government will announce an itr deadline extension for the Assessment Year (AY) 2025-26, it is time to reconsider. Filing your Income Tax Return (ITR) early is not just about ticking off a compliance box; it is a critical financial practice that safeguards your hard-earned money. This comprehensive guide explores the hidden risks of waiting for a deadline shift and outlines how early filing protects your financial health.
What is the ITR Deadline Extension Trend?
The itr deadline extension refers to an official announcement by the Central Board of Direct Taxes (CBDT) that moves the final date for filing income tax returns beyond the standard statutory calendar. For individual taxpayers, salaried employees, and non-audit business cases, the standard deadline under Section 139(1) of the Income Tax Act is July 31 of the relevant Assessment Year.
Historically, the government has stepped in to extend this date under extraordinary circumstances. In the past, massive server crashes on the e-filing portal, structural overhauls of tax forms, or national disruptions like the COVID-19 pandemic prompted the CBDT to grant additional time. These extensions were designed as relief measures to ensure that systemic failures did not penalize honest taxpayers.
Unfortunately, many taxpayers have misinterpreted these past administrative reliefs as a annual guarantee. This has created a recurring cycle where millions of individuals delay their filings until the final week of July, actively tracking social media platforms and news outlets for any rumor of an itr deadline extension. When an extension is not granted, this behavior triggers chaotic portal traffic, clerical errors, and immediate financial liabilities.
Current Situation and Latest Updates for AY 2025-26
As of the current filing season for Assessment Year 2025-26 (Financial Year 2024-25), the Ministry of Finance and the Income Tax Department have maintained a strict stance regarding the timeline. The official statutory deadline for filing individual income tax returns remains firmly fixed at July 31.
The government has continually upgraded the technical infrastructure of the e-filing portal. Enhanced server capacities, automated data population, and real-time processing systems have drastically reduced portal glitches compared to previous years. Because the e-filing system is operating smoothly and processing millions of returns daily, institutional insiders emphasize that there is no structural justification for the government to announce an itr deadline extension.
Tax professionals and financial advisory bodies across India are strongly urging taxpayers to discard any expectations of a deadline shift. The government’s clear objective is to streamline tax compliance, encourage disciplined financial behavior, and ensure timely revenue collection. Relying on an unconfirmed, speculative itr deadline extension this year leaves taxpayers highly vulnerable to automated statutory penalties the moment the clock strikes midnight on July 31.
Why Early Filing and Avoiding the Extension Trap is Crucial
Filing your tax return early—well before the shadow of the July 31 deadline—is a proactive strategy that offers immense peace of mind. When you stop waiting for an itr deadline extension, you gain complete control over your financial documentation, enabling you to file a flawless, compliant return.
Furthermore, early filing accelerates the processing of your tax refunds. The Income Tax Department processes returns largely on a first-come, first-served basis. By submitting your return early, you position your file at the front of the processing queue, allowing the system to verify your data and credit your refund directly into your bank account weeks ahead of the massive end-of-season rush.
Key Highlights: The True Cost of Delaying Your ITR
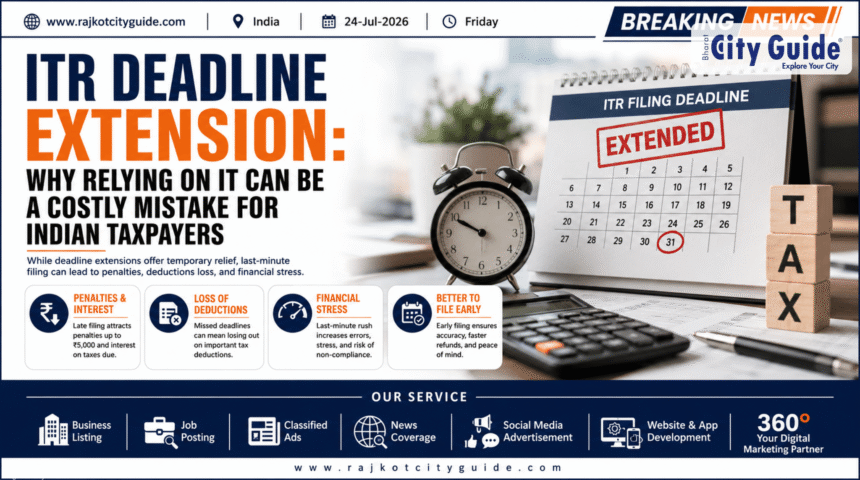
- Instant Financial Penalties: Missing the July 31 deadline triggers an automatic late filing fee under Section 234F.
- Accumulating Interest Charges: Delayed filing incurs a monthly compounding interest charge on any unpaid tax liabilities.
- Forfeiture of Financial Losses: Taxpayers lose the legal right to carry forward capital losses to offset future gains.
- Delayed Tax Refunds: Late filing pushes your return to the bottom of the processing pile, stalling your refund for months.
- Portal Congestion Risks: Waiting until the final days exposes you to potential local network errors and intense traffic delays on the e-filing website.
Detailed Complications of Relying on an ITR Deadline Extension
Addressing Data Mismatches in AIS and Form 26AS
A primary danger of delaying your tax filing in hopes of an itr deadline extension is encountering unexpected data mismatches. When a taxpayer logs into the e-filing portal during the chaotic final week of July, they frequently discover discrepancies between their personal records and government data systems.
The Annual Information Statement (AIS) and Form 26AS aggregate financial data reported by third-party entities like banks, mutual fund houses, and employers. If a commercial bank misreports the Tax Deducted at Source (TDS) on your fixed deposit interest, or if your employer uploads incorrect salary details, your filed return will flag an immediate error.
Resolving these structural errors takes time. You must reach out to the deductor, request a correction, and wait for them to file a revised TDS return. Filing early gives you the crucial time frame needed to address these mismatches systematically, ensuring you claim your full, legitimate tax credits without missing the deadline.
Re-Evaluating Early-Year Tax Regime Choices
Many salaried professionals blindly stick with the specific tax regime—either the Old Tax Regime or the New Tax Regime—that they declared to their corporate human resource departments at the beginning of the financial year. However, initial declarations are often based on rough estimates, and financial realities can change drastically over twelve months.
A mid-year financial pivot, such as taking out a new home loan, enrolling in a higher education program, or purchasing an extensive family health insurance policy, can completely tilt the scales of tax efficiency. The ideal choice between the old and new tax structures depends entirely on your finalized, actual deductions versus the lower slab rates of the default new regime.
Waiting for an itr deadline extension forces you to make hurried, uncalculated choices under immense temporal stress. Conversely, cross-checking both tax regimes early with definitive, final numbers guarantees that you select the exact pathway that minimizes your legal tax liability.
Forfeiture of the Right to Carry Forward Losses
The Income Tax Act provides a highly beneficial provision that allows taxpayers to carry forward unadjusted losses to subsequent financial years. This applies to short-term and long-term capital losses from equity trading, mutual funds, real estate sales, and business losses.
These losses can be set off against future taxable gains, substantially lowering your tax liabilities in upcoming years. However, this legal benefit comes with a strict condition: you must file your initial return before the original statutory due date specified under Section 139(1). If you miss the July 31 deadline because you were casually expecting an itr deadline extension, you completely forfeit the right to carry forward these valuable losses, damaging your long-term investment yields.
Statutory Penalties and Financial Implications of Missing the Deadline
If you choose to delay your submission and the government declines to issue an itr deadline extension, you face immediate statutory consequences established under the Income Tax Act.
Late Filing Fee (Section 234F)
The moment you file a belated return after July 31, the e-filing system automatically levies a mandatory late fee under Section 234F:
- Rs 5,000: Standard penalty for taxpayers whose total income exceeds Rs 5 lakh.
- Rs 1,000: A reduced cap designed for small taxpayers whose total income does not exceed Rs 5 lakh.
Accumulation of Penal Interest (Section 234A)
If you have outstanding tax liabilities that were not covered by Advance Tax or (TDS) Tax Deducted at Source, waiting around for an itr deadline extension becomes incredibly expensive. Under Section 234A, interest is charged at a strict rate of 1% per month, or part of a month, on the total amount of unpaid tax. This interest begins compounding immediately after the July 31 deadline and continues to build until the day you officially submit your return.
Step-by-Step Checklist for a Penalty-Free ITR Filing
To avoid the anxiety of tracking updates for an itr deadline extension, follow this streamlined checklist to complete your filing seamlessly:
1. Gather Essential Documents
- Form 16: Obtain this comprehensive salary and TDS breakdown from your employer.
- Form 16A / 16B / 16C: Collect these from banks or buyers for non-salary income and TDS deductions.
- Interest Certificates: Download statements from your saving bank accounts and fixed deposits.
- Capital Gains Statements: Secure detailed transaction logs from your equity brokers or mutual fund platforms.
2. Verify Your Government Tax Profiles
- Log into the official e-filing portal and thoroughly review your Annual Information Statement (AIS).
- Check the Taxpayer Information Summary (TIS) for simplified transaction overviews.
- Cross-reference the values against Form 26AS to ensure all deducted taxes are properly credited to your Permanent Account Number (PAN).
3. Compare Regimes and File Electronically
- Use the online tax calculators to test your total liability under both the Old and New tax regimes.
- Select the correct ITR Form (ITR-1 for simple salary cases, ITR-2 or ITR-3 for capital gains and business incomes).
- Submit the form and immediately complete the e-Verification process using Aadhaar OTP or net banking to prevent your return from being declared invalid.
Advantages of Timely Filing vs. Waiting for an Extension
| Financial Parameter | Filing Early (Before July 31) | Waiting for an ITR Deadline Extension |
|---|---|---|
| Late Filing Fee (Sec 234F) | Nil | Rs 1,000 to Rs 5,000 if extension is denied |
| Penal Interest (Sec 234A) | None | 1% per month on outstanding tax liability |
| Carrying Forward Losses | Allowed fully for equity, property, and business | Completely forfeited under a belated return |
| Refund Processing Speed | Rapid; prioritized by early automated queues | Highly delayed due to system backlogs |
| Data Correction Window | Ample time to dispute mistakes with banks/employers | Extremely rushed; high risk of defective return notices |
Who Benefits the Most from Early Filing?
Salaried Professionals
Salaried individuals with predictable income streams usually receive their Form 16 by mid-June. Waiting for an itr deadline extension offers absolutely no benefit to this group. Filing immediately after receiving Form 16 clears your compliance calendar and secures any eligible tax refunds quickly.
Active Investors and Traders
Individuals actively dealing in stocks, mutual funds, and crypto assets manage multiple data sets across different brokers. They frequently face reporting mismatches in their AIS. Filing early gives these investors the necessary time to reconcile variations and preserve their right to carry forward capital losses.
NRIs and High-Net-Worth Individuals (HNIs)
Taxpayers with foreign assets, global incomes, or complex high-value domestic investments require deep evaluation to ensure compliance with disclosure schedules. Leaving these intricate calculations to the final hours of an uncertain itr deadline extension is a recipe for compliance failures and subsequent scrutiny notices.
Future Expectations: The Paradigm Shift in Indian Tax Administration
The long-term outlook clearly indicates that the era of routine, casual deadline adjustments is firmly over. The Income Tax Department is progressively moving toward a ecosystem powered by artificial intelligence, real-time data syncing, and instant processing.
Future compliance models aim to pre-populate nearly every field of a taxpayer’s return using instantaneous data feeds from financial systems. As data synchronization becomes instantaneous, the window for manual errors narrows, and the administrative justification for granting an itr deadline extension disappears entirely. Taxpayers must align their habits with this digitized reality and treat July 31 as an absolute, unmoving commitment.
Frequently Asked Questions (FAQs)
What happens if I do not file my ITR by July 31 and there is no ITR deadline extension?
If you miss the July 31 cutoff and the government does not announce an official itr deadline extension, your return will be categorized as a “Belated Return” under Section 139(4). You will be forced to pay a mandatory late filing fee under Section 234F, which can go up to Rs 5,000 depending on your total taxable income. Additionally, if you have any unpaid tax liabilities, you will face an interest penalty of 1% per month under Section 234A, calculated from August 1 until the date you finally file. You also forfeit the privilege to carry forward any capital losses to reduce your future tax liabilities.
Can I revise my income tax return if I file early and discover an error later?
Yes, absolutely. One of the greatest advantages of filing your return early instead of tracking an itr deadline extension is the ability to easily correct mistakes. If you discover that you missed declaring an income source or forgot to claim an eligible deduction, you can submit a “Revised Return” under Section 139(5). If your original return was submitted before the July 31 deadline, your revised return replaces the original file seamlessly without attracting any late fees or administrative penalties, giving you a valuable safety margin.
Does an ITR deadline extension affect the timeline for getting my tax refund?
Yes, it impacts it significantly. The Income Tax Department leverages automated processing systems that operate largely on a chronological, first-come, first-served sequence. When you file early in June or early July, your return enters an uncrowded processing pipeline, often resulting in swift verification and quick refund issuance. If you delay your filing because you are waiting for a potential itr deadline extension, your return gets grouped with millions of late submissions. This immense volume creates severe backlogs, delaying your tax refund by several months.
Is the New Tax Regime selection affected if I miss the July 31 deadline?
Yes, it can introduce serious complications. Under the current tax laws, the New Tax Regime is the default option for all individual taxpayers. If you wish to opt out and choose the Old Tax Regime to claim deductions like Section 80C, HRA, or home loan interest, you must file your return within the original statutory deadline outlined under Section 139(1). If you miss the July 31 date because you expected an itr deadline extension that never happened, you may lose the opportunity to choose the Old Tax Regime entirely, forcing your tax calculation into the default New Tax Regime and potentially increasing your final tax bill.
How do I check if the government has officially announced an ITR deadline extension?
To check the authenticity of a rumored deadline change, always cross-reference official government channels rather than relying on viral social media posts. Valid updates regarding an itr deadline extension are published directly on the official Income Tax Department e-filing portal or via press releases from the Central Board of Direct Taxes (CBDT). The department’s official social media handles also post real-time updates. If these platforms do not display an official notification, the July 31 deadline remains legally binding.
What are the main documents I need to verify before the filing deadline to avoid errors?
To file a precise, error-free return before the deadline, you must match your personal accounts against three primary documents provided on the e-filing portal: the Annual Information Statement (AIS), the Taxpayer Information Summary (TIS), and Form 26AS. Along with these, verify your Form 16 from your employer, capital gains reports from your investment brokers, and interest certificates from your banking institutions. Reconciling these documents early eliminates the risk of receiving data mismatch notices from the tax department.
Conclusion
Relying on a speculative itr deadline extension is a hazardous financial gamble that exposes you to unnecessary penalties, accruing interest, and the permanent loss of valuable tax benefits. While the government has stepped in with extensions during past crises, the modern e-filing ecosystem is highly stable, making automated deadlines firm and unyielding.
Filing your income tax return early is the single most effective way to eliminate compliance anxiety. By taking charge of your financial data in June or early July, you give yourself adequate time to address data mismatches in your AIS, accurately evaluate the most cost-effective tax regime, and secure rapid processing for your tax refunds.
Do not let procrastination complicate your financial health. Avoid the last-minute panic, ignore the rumors surrounding an itr deadline extension, and log into the e-filing portal to complete your tax compliance smoothly today.